



Download
iLearn application
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App


Consider the four pillars of personal finance as the critical beams on which you establish your financial home. Based on your choices, you alone hold the key that determines whether your financial house is solid or may fall apart. When looking into every pillar of your finances, you need to collectively view the larger picture rather than focus on them individually.
For instance, you may be saving regularly towards your retirement but ignoring the mountain of debt that could potentially eat into all of your savings. Let's look at how to decode the four pillars of personal finance and why you need to work on all at the same time to ensure the integrity of your financial home.
How does debt fit into building a solid financial foundation? That's because, when creating your financial future, debt can quickly turn into a swamp. And if you would know about swamps, it appears shaky, doubtful and easily yields to pressure and absorbs everything resting on it or falling into it.
Debt needs to be taken into consideration when maintaining your financial nest. If not managed properly, one could drown in it easily. But debt is also a good tool if used carefully and in the proper manner.
For instance, one example of good debt is home loans. As a form of debt, home loans or property loans can be responsibly used as leverage when repaid on time and in full. Besides, a home loan can help you purchase a new house or property that would otherwise take decades to pay the money upfront.
When understanding your debt, look into your Debt to Income ratio [DTI] — your monthly debt repayments divided by your monthly income. This is a snapshot at any given time in your life that shows the amount of debt you can afford to take and the amount of debt you are currently handling.
Lenders look into DTI to evaluate a borrower's ability to make timely payments on various debts borrowed. When examining your debt pillar, find out:
Additional read: How to carefully comb through financial statements
Saving money may not be as enticing as spending. But no matter how boring saving money is, it gives you peace of mind that spending does not.
As the cornerstone of your personal finances, your savings pillar is the first foundation you need to place -- all other pillars of your financial house rest on the cornerstone. Hence, it would help if you supported this pillar with all your might. Some ways to do so is to:
Reward yourself first; set it and forget it. Unfortunately, most people tend to look the other way around, which means they pay bills first and then save whatever remains. No matter how much you make, remember to pay yourself first by putting your money into a savings account before paying for anything else
Sticking to a budget can reveal areas where you may be able to save even more. The art of budgeting can aid you in maintaining an active role in your personal finances and cutting down discretionary spending that you can put towards better use, such as repaying debt or saving more.
Spending less than what you make can go a long way for a better tomorrow. Take small steps to sacrifice a little every day and avoid buying things you don't need to build on your savings.
Saving 6 to 9 months of obligatory expenses can help you deal with emergencies. So whether you need to pay an unexpected hospital bill, address basic costs that may arise due to the loss of a job, a sudden leaking roof or a broken car. When you need instant money at hand, your stockpiled emergency funds will come in handy.
The sooner you begin to save towards retirement, the better off you may be. A critical factor that has the best interest at heart is time. That means the longer you remain invested, the more time it will have to continuously compound across market cycles.
As part of the same pillar, asset management is also crucial. Assets are regarded as valuable items that you can turn to cash when you need the money. This could include real estate, stocks and securities, equity in your home, whole insurance policies, precious jewellery and much more.
The key to owning the right asset lies is in its ability to be converted into liquid cash in a short time frame. Since one can never wholly escape risk, you can use the weapon of diversification, which means not setting all your eggs into one investment basket. Spread your investments across assets to give you the potential of earning revenue and minimizing the loss. Investing through Exchange Traded Funds [ETFs] and mutual funds offer you instant diversification without the need to monitor individual securities.
Additional read: Importance of investing and where to invest
How you plan your life is the fourth pillar that supports every other aspect of your life. Purchasing life insurance, estate planning, putting a will in place, creating a trust fund, filing your taxes etc., are aspects that affect your financial setting.
As a crucial piece of your personal finance, selecting the right health and life insurance is critical. You want to make sure that your family is not financially burdened should anything happen to you. And for that, life insurance can take care of your child's education, family needs and more. As an essential pillar of your personal finance, planning for future events can give you peace of mind if you are no longer around to take care of your family.
When building a solid personal finance background, incorporate all of the above aspects to keep your money in check. Meet all your dreams and ambitions by starting to work on these four pillars in your life today.
Take a good look at your debt, income, assets, and long-term expenses to know your vital financial signs. Look for ways to strengthen the four pillars of your personal finances by increasing your investments, decreasing debt and getting your income and expenses in proper balance. If you're in search of valuable guidance on how to save and invest for your future, speak to an expert financial advisor to get you started.


Understand contango in commodity trading, how futures prices differ from spot prices, and how financing, storage and insurance costs influence commodity pricing.
 214 views
 1 minutes
 19 Oct 2026
Copper is a widely used base metal known for its electrical and thermal conductivity, strength, ductility and corrosion resistance. It is used across electrical wiring, construction, machinery, power infrastructure and several industrial applications.
426 views
2 minutes
09 Oct 2026
Natural Gas is a widely traded energy commodity used for electricity generation, industrial activity, heating and other applications. Its prices can react sharply to weather, supply and demand, inventories, global energy markets and geopolitical developments.
704 views
1 minutes
30 Sep 2026
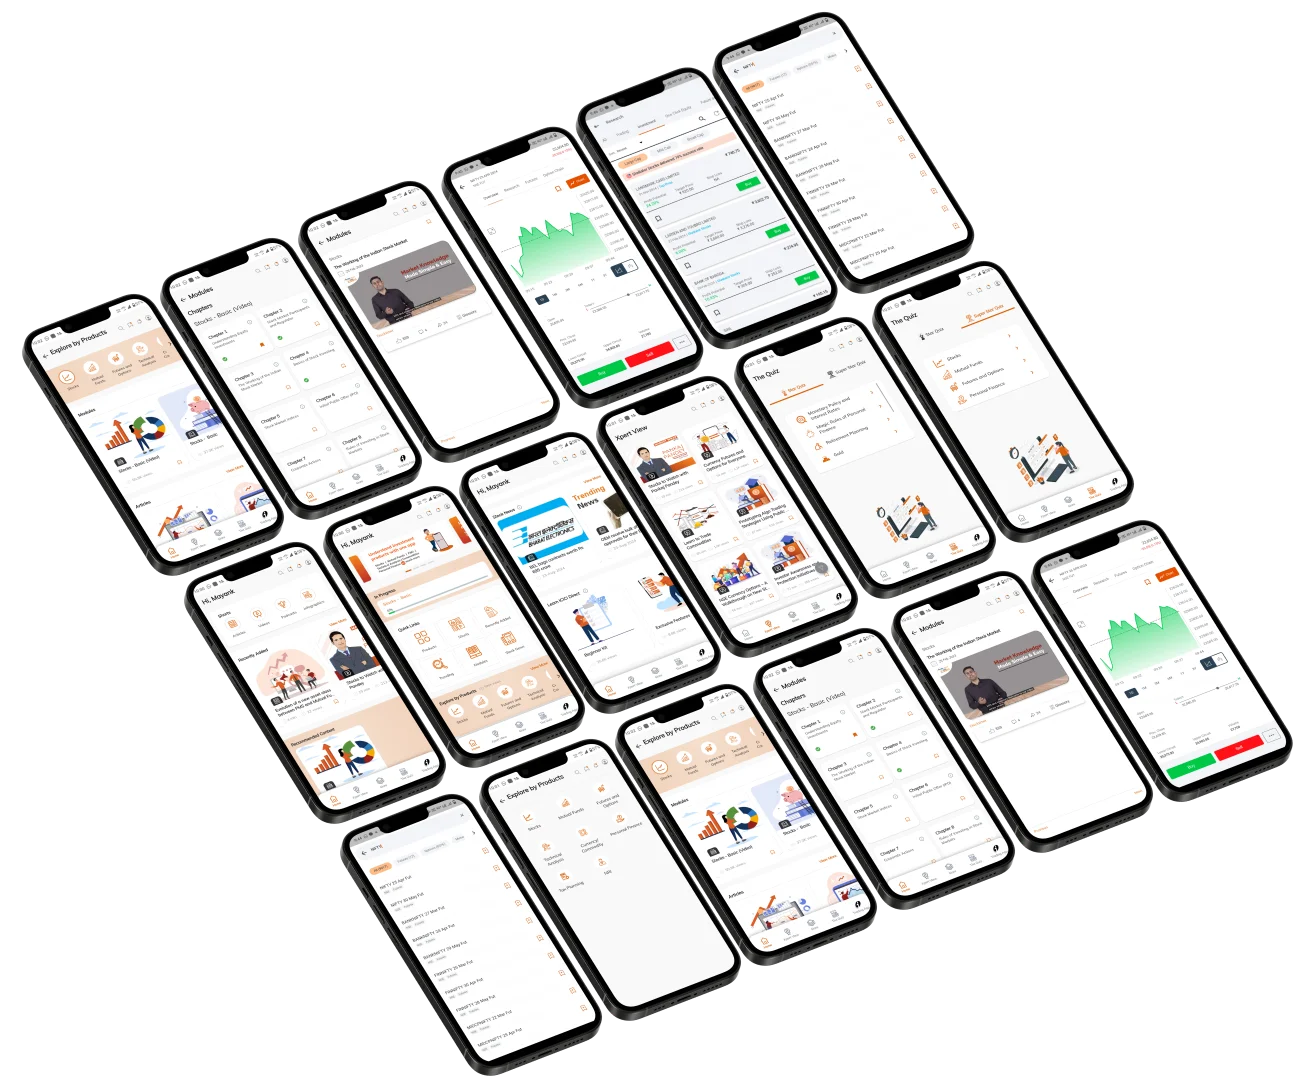
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App
