



Download
iLearn application
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App


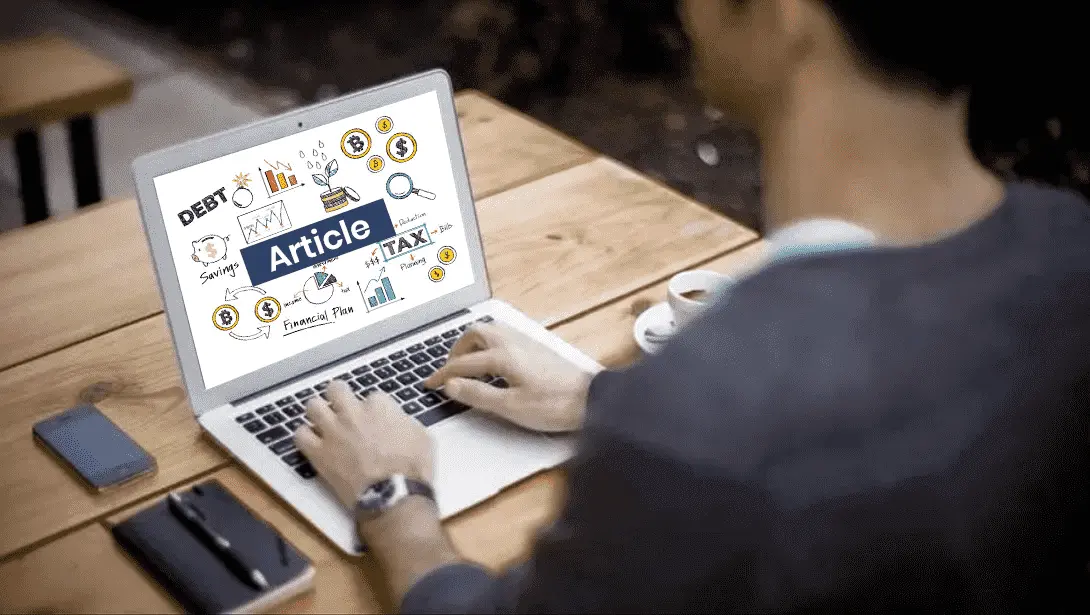
Who doesn’t love to have a surplus amount of wealth that they can use for many reasons?
At the outset, wealth creation sounds like a heavy concept to those who are new to the world of investing. However, as a starter, you certainly don’t need to be as good as some big-shot investor to create wealth. Simply speaking, you just need to start small, and take advantage of the compounding that happens when you regularly invest your savings, cut down your expenses and increase your investments incrementally.
But how should you even start with this entire process? That is exactly what we will be talking about in this article.
First and foremost, one needs to clearly understand that creating wealth is a step-by-step process and the earlier one starts, the better it will be for the long run.
Wealth creation requires a considerable amount of discipline in the way one manages their finances to set aside some money which can grow through investments.
1. Let’s understand the importance of life and health insurance
One of the best methods to financially protect your family in the event of something unfortunate is by purchasing a life insurance term plan. The insurance amount should preferably be around 15-20 times of your annual income. A 1-crore rupee term plan will cost you around 10-12k rupees per year, given that you purchased the term plan at around 28-29 years of age.
On top of life insurance, it is paramount to have a health insurance policy as well. A health insurance policy will financially safeguard you from the massive hospital bills if you ever were to get hospitalized. It is advisable to purchase a family floater policy, which covers all the immediate family members in a single policy
2. Set aside some money for Investments
You need to ensure that you are earning enough so that you can set aside some money as savings and for investment purposes. This is because there are some non-discretionary expenses like monthly house-rent, food costs, electricity and water bills and multiple other necessities which are essential.
Apart from these necessities, you need to ensure that you don’t spend too much money on discretionary items like dinner-nights or expensive products.
Following a monthly budget can help you allocate specific portions of your income towards necessities, savings and wants. Thrift spending needs to be controlled as much as possible. Ideally, you should save 20-30% of your income and in the initial years, you can even start with a relatively lower saving amount.
The money which you save after deducting expenses from your income can be invested through Systematic Investment Plans, or SIPs.
According to your financial goals of either having a retirement fund, holiday fund or a fund so that you can start your business, you can select a tenure of the SIP and the right mutual fund suitable to your risk profile and Investment time horizon.
Other than investing through SIPs in mutual funds, you can also plan to invest in some of the blue-chip stocks, but this requires you to monitor your investment portfolio regularly and actively. Long-term investments in the stock market are generally beneficial to beat inflation.
You also need some experience before you can try and actively invest in the stock market, so the best way forward as a beginner is to invest your savings through SIPs in an index fund while learning more about the markets. Alternately, if you want to Invest in direct stocks you may look at portfolio of stocks suggested by broking houses.
Additional Read: How does Share Market Works in India?
3. Avoid unproductive debt
You should try your level best to not fall into expensive and unproductive debt, like credit card outstanding or personal loans. These loans can be avoided if you refrain from incurring unnecessary expenses like buying the next high-end gadget and cautiously observing your spending patterns.
4. Have an emergency fund
It is always a good idea to have an emergency fund comprising of 6 months’ worth of expenses which can act as a cushion in the event of either a layoff, medical emergencies, or anything else.
5. Step up your investments
Once your income starts increasing, the portions of money which you set aside for investments should also increase proportionally, so that you can see exponential gains in the long run. You can do this by giving your SIP a top-up as your income increases year-on-year.
In the event of getting a bonus or the maturity amount for any of your previous investments, instead of spending it completely, you can invest a portion of this money. This can help in reaching your target amount faster.
And lastly, remember that in the long-run, diversification of your investment portfolio among multiple asset classes is paramount so that your wealth compounds and helps in offsetting the risks due to market volatility. You can keep a mix of asset classes like equity, debt, gold in your portfolio. You can keep (100 - your age) % in equity and the remaining portion in debt as a thumb rule. It means, if you are 30 years old, you should keep 70% of your portfolio in equity.
Additional Read: How to create a portfolio in share market?


Copper is a widely used base metal known for its electrical and thermal conductivity, strength, ductility and corrosion resistance. It is used across electrical wiring, construction, machinery, power infrastructure and several industrial applications.
 150 views
 2 minutes
 09 Oct 2026
Natural Gas is a widely traded energy commodity used for electricity generation, industrial activity, heating and other applications. Its prices can react sharply to weather, supply and demand, inventories, global energy markets and geopolitical developments.
322 views
1 minutes
30 Sep 2026
Gold is more than a precious metal. It is a safe-haven asset, investment avenue, central-bank reserve asset and industrial commodity. For a commodity trader, understanding both Gold's fundamentals and the contract being traded is important.
455 views
3 minutes
23 Sep 2026
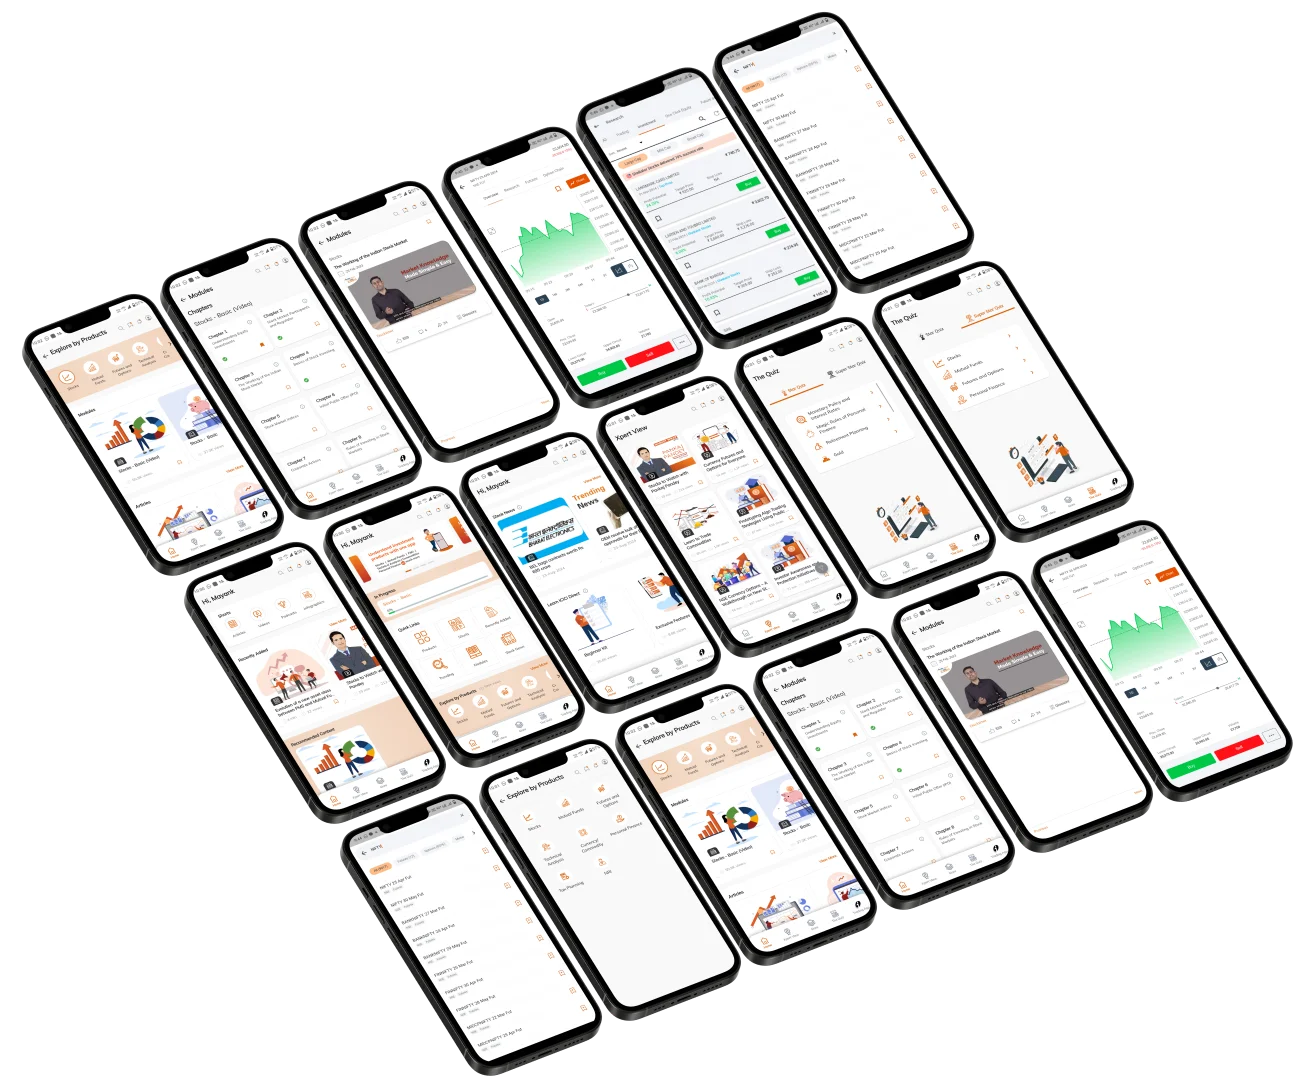
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App
