




Download
iLearn application
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App


Every year, there are additions or deletions to taxation rules in India. These are announced in the Budget report that is presented in February. This year, there have been some interesting financial changes that will impact individuals. Some of these are welcome changes, while others may increase your tax burden. Nevertheless, staying on top of the new income tax rules will help you with tax planning and ensure you file your income tax returns correctly.
1. Taxation on Interest Earned on EPF Accounts
The new income tax rules have introduced a taxation component for interest earned on Employee Provident Funds. If an employee contributes Rs. 2,50,000, any interest earned on the excess contribution will be taxable. The taxation threshold has been set at Rs 5,00,000 for individuals who don’t receive a contribution from employers, such as government employees. A separate account for the additional interest earned will be created to make taxation easier.
2. Tax on Cryptocurrencies and Virtual Digital Assets
In a move that sort of taxation on cryptocurrencies and virtual digital assets (VDA) in India, the government has announced a flat 30% tax on gains from cryptocurrencies and other VDA. The government has also made it clear that no deductions will be allowed on transactions made for virtual digital assets, and the losses from one VDA cannot be set off against gains from other VDAs.
3. Updated Income Tax Returns Filing Extended
As a taxpayer, you can now file revised or updated income tax returns within two years from the end of the assessment year. This will give you more time to correct any errors or disclose additional income that you did not in the initial filing. However, taxpayers need to pay an additional tax of 25% to 50% on the tax and interest due on the additional income.
4. NPS Deduction for State Government Employees
Suppose you are an employee of any State government. In that case, you will be able to claim a deduction under Section 80CCD(2) for NPS contributions made by your employer up to 14% of your basic salary and dearness allowance. Earlier, this deduction was 10%.
5. Tax Exemption on Covid-related Financial Assistance
If you have received money for Covid treatment from an employer or got money up to Rs. 10,00,000 on the death of a family member due to Covid, this amount will not be considered income, therefore becoming exempt from taxation.
6. Tax Relief for Insurance Bought for Disabled Persons
Under the provisions of Section 80DD, parents or guardians of a disabled person can now claim a tax deduction on a life insurance policy purchased for a disabled person, even if the payout starts while they are alive.
These are some of the significant income tax rules that will impact you from April 1st, 2022. Staying abreast of the latest financial changes can help you improve your tax planning and ensure you don’t miss out on any key declarations while filing your income tax returns.


Gold is one of the world's most actively traded precious metals and is widely used for investment, jewellery and industrial applications. It is also considered a safe-haven asset during periods of economic or market uncertainty.
 354 views
 3 minutes
 07 Sep 2026
In this article, we’ll explore the three exchanges that matter most: NYMEX, COMEX, and the London Metal Exchange (LME) and their link with MCX.
526 views
1 minutes
31 Aug 2026
Explore the meaning of a mainboard IPO, SEBI's eligibility routes, NSE and BSE listing rules, key benefits, and the checks investors should make before applying.
2 k views
4 minutes
13 Aug 2026
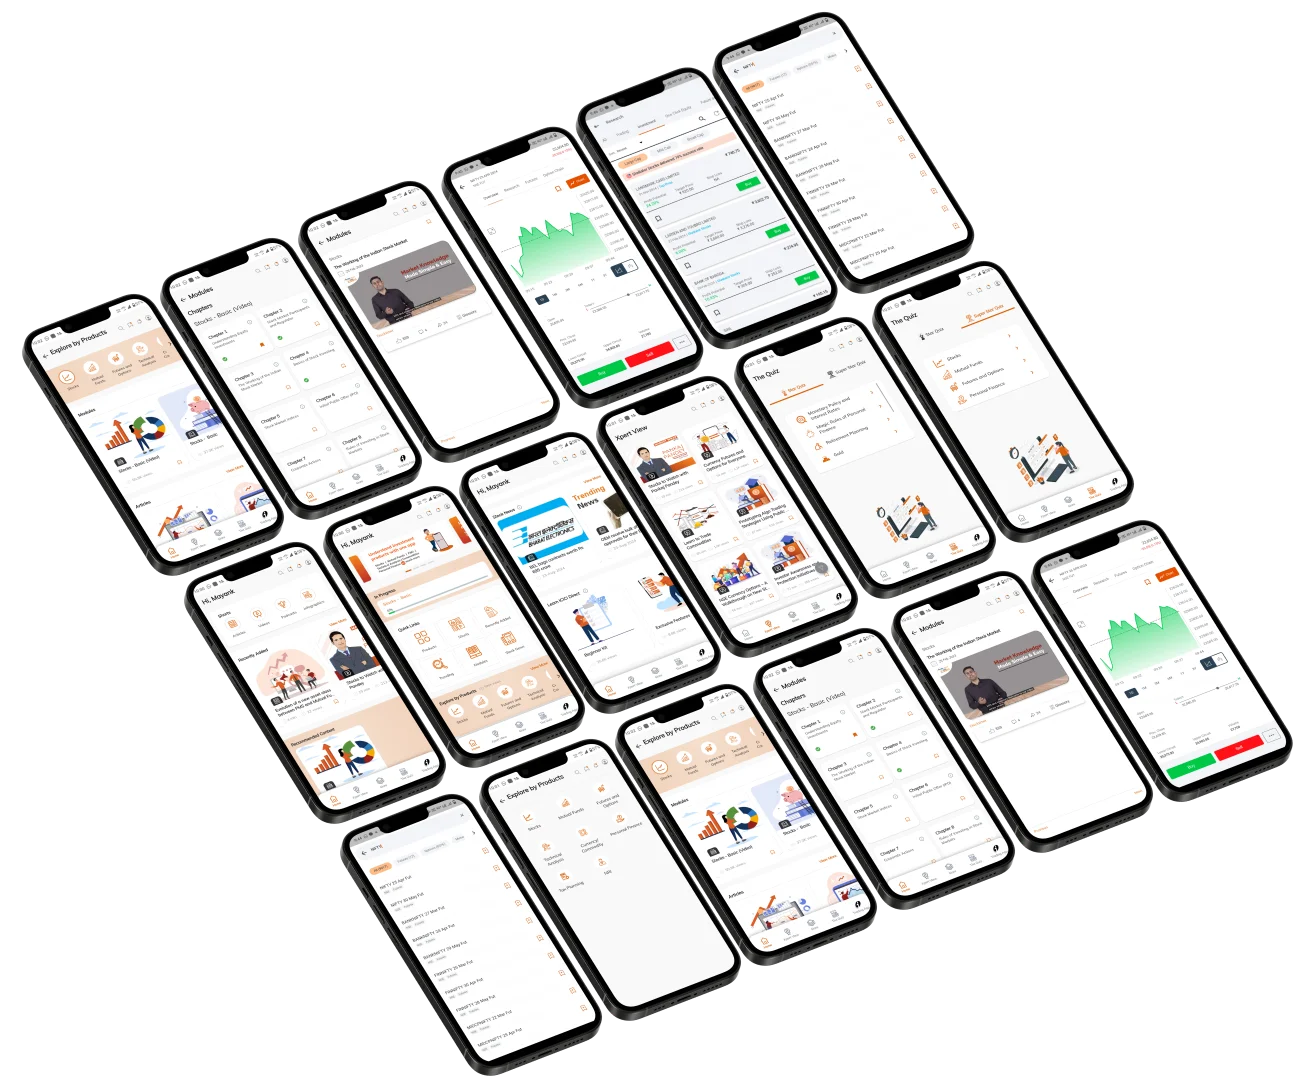
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App
Elevate Your Financial Knowledge with the
ICICI Direct iLearn App
